Pensions are also tied to the economic cycle—a fancy way of saying “the economy has mood swings.” When the economy slows down, companies earn less, lay off people, and pay fewer taxes. That can reduce the value of your pension fund, especially if you’re in a “defined benefit” plan where your payout depends on your employer’s health.
For example, many corporate pension funds in the UK have massive deficits—they owe more than they have. The Pension Protection Fund reported a £190 billion deficit in 2026. That’s billion with a B, which is a lot of zeros and a lot of sleepless nights for actuaries. Don’t worry, though; the government steps in to protect most of your money, but it’s still a bumpy ride.
Your Employer Might Be a Party Pooper
Sometimes, your pension drops because your employer decides to contribute less or change the terms. This is rare, but it happens—like that friend who “forgets” to pay for their round at the pub. Auto-enrollment requires at least 3% from them, but they can legally reduce it in some circumstances. Check your contract. If you see “minimum contribution,” it’s code for “we’re doing the bare minimum.”
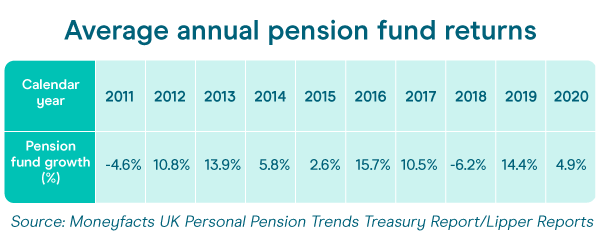 Why does my pension go up and down? | Moneybox | Save and Invest
Pro tip: never assume your employer loves you enough to max out their contribution. They might, but it’s safer to treat them like a cat: they’ll do what they want, and you’re just along for the ride.

