
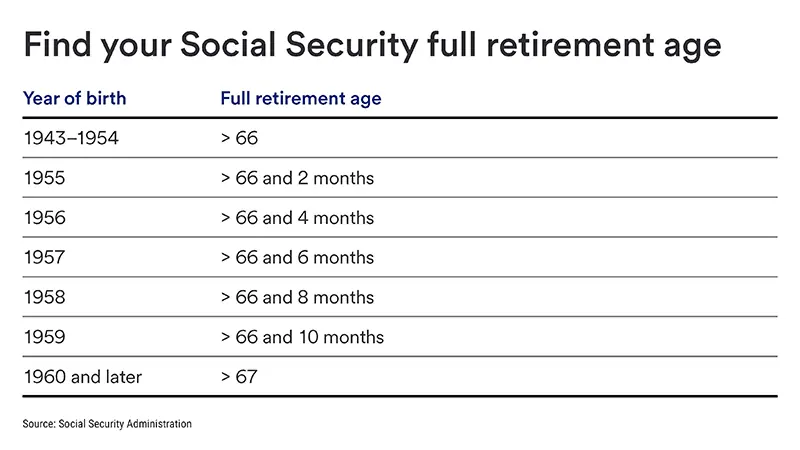
Remember when your teacher said “full retirement age” was 67? Well, the government did set that for Social Security in the US, but you don’t have to obey it like a traffic light. You can actually choose to start collecting checks as early as 62, or wait all the way until 70 to get a bigger monthly bonus. It’s like deciding when to eat dessert first—are you the type who needs the sweet now, or the one who savor it later for a bigger slice?
But here’s the cool part: your retirement age might not be 67 at all. Maybe it’s 45 if you’re a super-saver and live in a van down by the river. Or maybe it’s 75 because you love your job and your brain needs puzzles to feel alive. Isn’t it wild that you get to decide?
The “Boomerang” Age
Here’s a fun thought: what if you don’t retire once, but twice? Some people “retire” at 55, get bored of golf, and start a part-time cat cafe. They work, take a break, then work again—like a boomerang that keeps coming back. Your retirement age might be a range, not a point. That’s like saying you’ll retire somewhere between 55 and 70, depending on how much you like sleeping in.
Think of it like a road trip. You can gun it to the finish line (age 65) or take scenic detours (semi-retirement at 50 with a freelance gig). The question isn’t “what age?”—it’s “what kind of journey sounds fun to you?”
 Social Security Retirement Benefits Questions and Answers | U.S. Bank

