
If you have between 10 and 34 years, you’ll get a partial pension. Think of it as the “budget airline” version: you still get a seat, but you might have to pay for your own peanuts.
You need at least 10 qualifying years to get any state pension at all. Below that? Nada. Zero. Zilch. The state basically says, “Thanks for playing, but your pension is a myth, like a unicorn or a quiet toddler.”
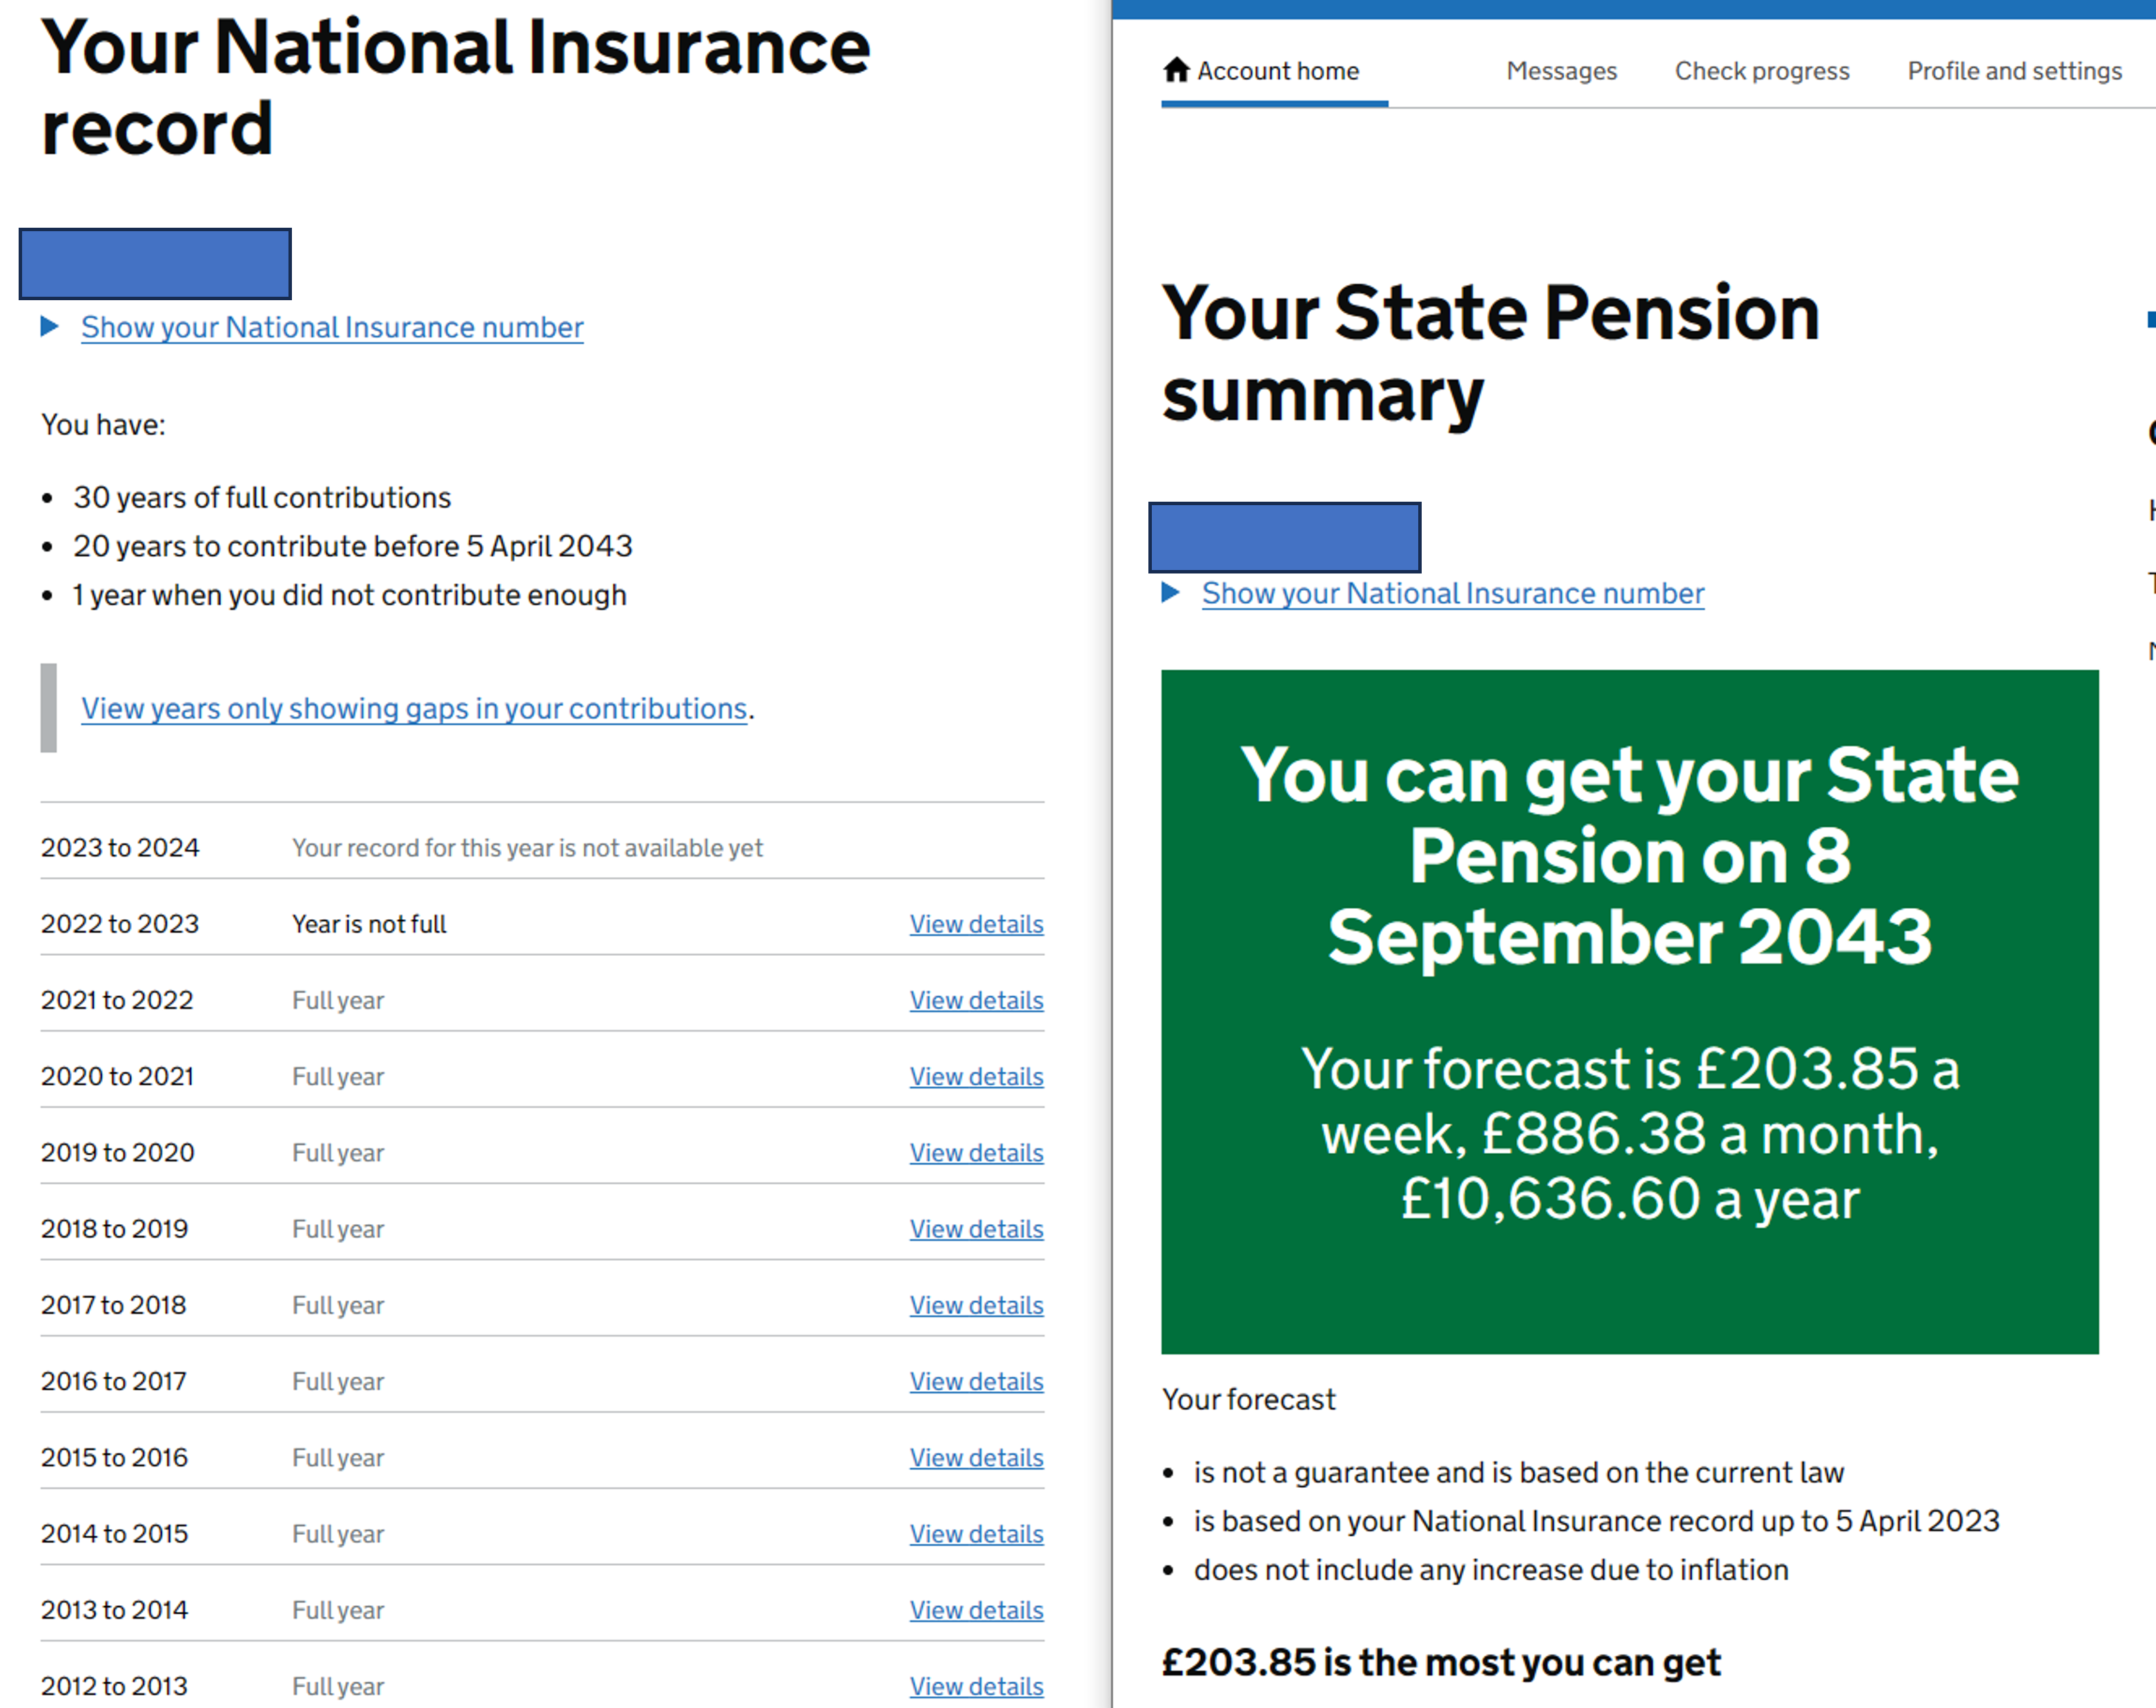 Only 30 years NI contributions but max pension already forecasted
But don’t panic—if you’re short, you can often buy extra years (called voluntary contributions). It’s like topping up your Oyster card before a long journey. You usually have a window to do this, so check online before it’s too late.
The ‘Old’ vs ‘New’ Pension Confusion
If you’re a man born before 6 April 1951, or a woman born before 6 April 1953, you’re on the old system—and you need 30 years for the full amount. That’s like the “retro edition” of the pension, with slightly different rules and possibly more wrinkles.
For everyone else (born after those dates), it’s the new State Pension—the one with the 35-year rule. So if you’re younger than a certain age, welcome to the club. The average age of the club is… well, let’s just say the playlist is mostly 80s hits.
One more twist: if you’ve been contracted out of the Additional State Pension (via a workplace pension), you might get a lower new State Pension. It’s like ordering a full English breakfast but being told, “Sorry, the beans are extra.” Check your National Insurance record online.

