
First, don’t panic. Declaring HRT isn’t like confessing a secret crime. Most insurance providers will cover you with a smaller additional premium or even no extra charge. Some will actually say, “Cool, that’s totally normal.” Especially if you’ve been stable for a while.
Here’s your cheat sheet:
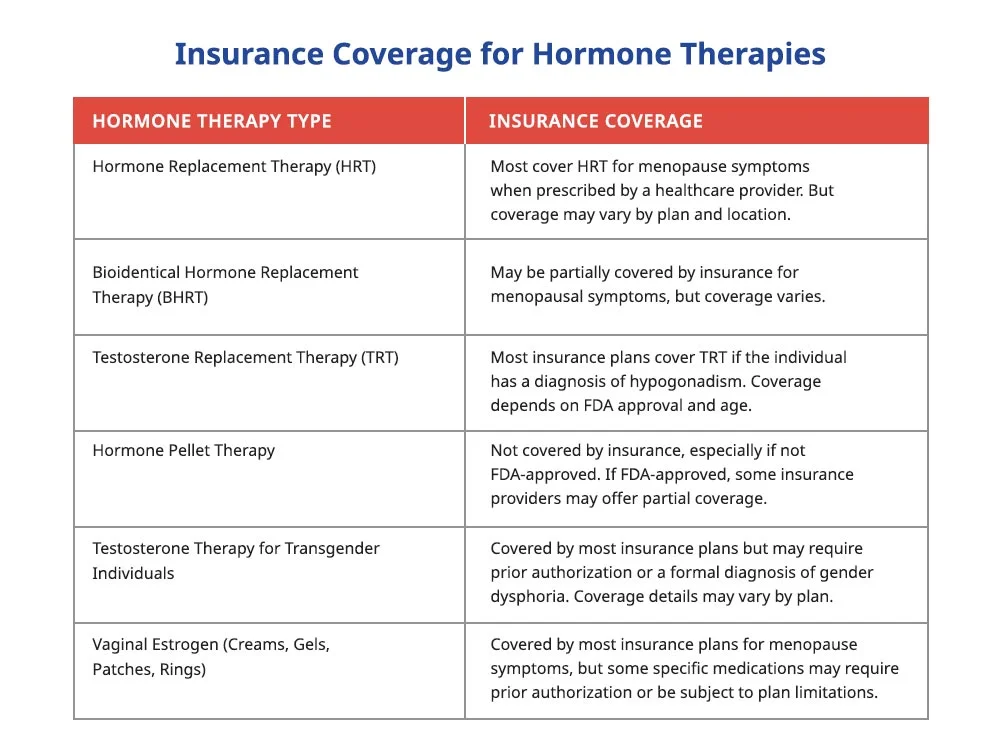 Does Insurance Cover Hormone Replacement Therapy? - Exceed Healthcare
- Be specific. Say “Estradiol patch, 50 mcg, twice weekly.” Don’t just say “hormones.”
- Mention reason. “For menopause management” or “Gender-affirming therapy.” They need the context.
- Check your policy online. Many insurers have a dropdown menu for “Hormonal Replacement Therapy.” Use it.
And here’s a fun twist: some companies will actually waive the extra charge if your HRT is prescribed for a common reason. They see “menopause” and think, “Ah, a standard life thing.” They see “testosterone for low libido” and think, “Okay, not a crisis.”
But if you lie? That’s a different story. Lying is like eating a ghost pepper before a marathon: a painful, avoidable mistake.
The “What If I Forget?” Amendment
Let’s be real. You might forget to declare it because you’re distracted by packing your inflatable flamingo. That happens. If you realize after buying the policy, call them immediately. Most insurers have a 14-day cooling-off period where you can add information without penalty.
Do it with a smile. Say, “Oops, I forgot to mention my estrogen. My bad.” They’ll probably just add a note and move on. No one sends the hormone police.
But if you wait until you’re in a Mexican clinic needing a blood transfusion, that’s a whole different vibe. And it’s a very expensive vibe.

