
Mortgage terms are weird. Did you know a two-year term is often called a “starter”? As if you’re just tasting your debt. And a five-year? It’s the “settler”—like you’re marrying your bank.
One bank in Canada actually uses emoji in their mortgage ads. No joke. They put a rocket for two-year and a turtle for five-year. Choose wisely, space cowboy.
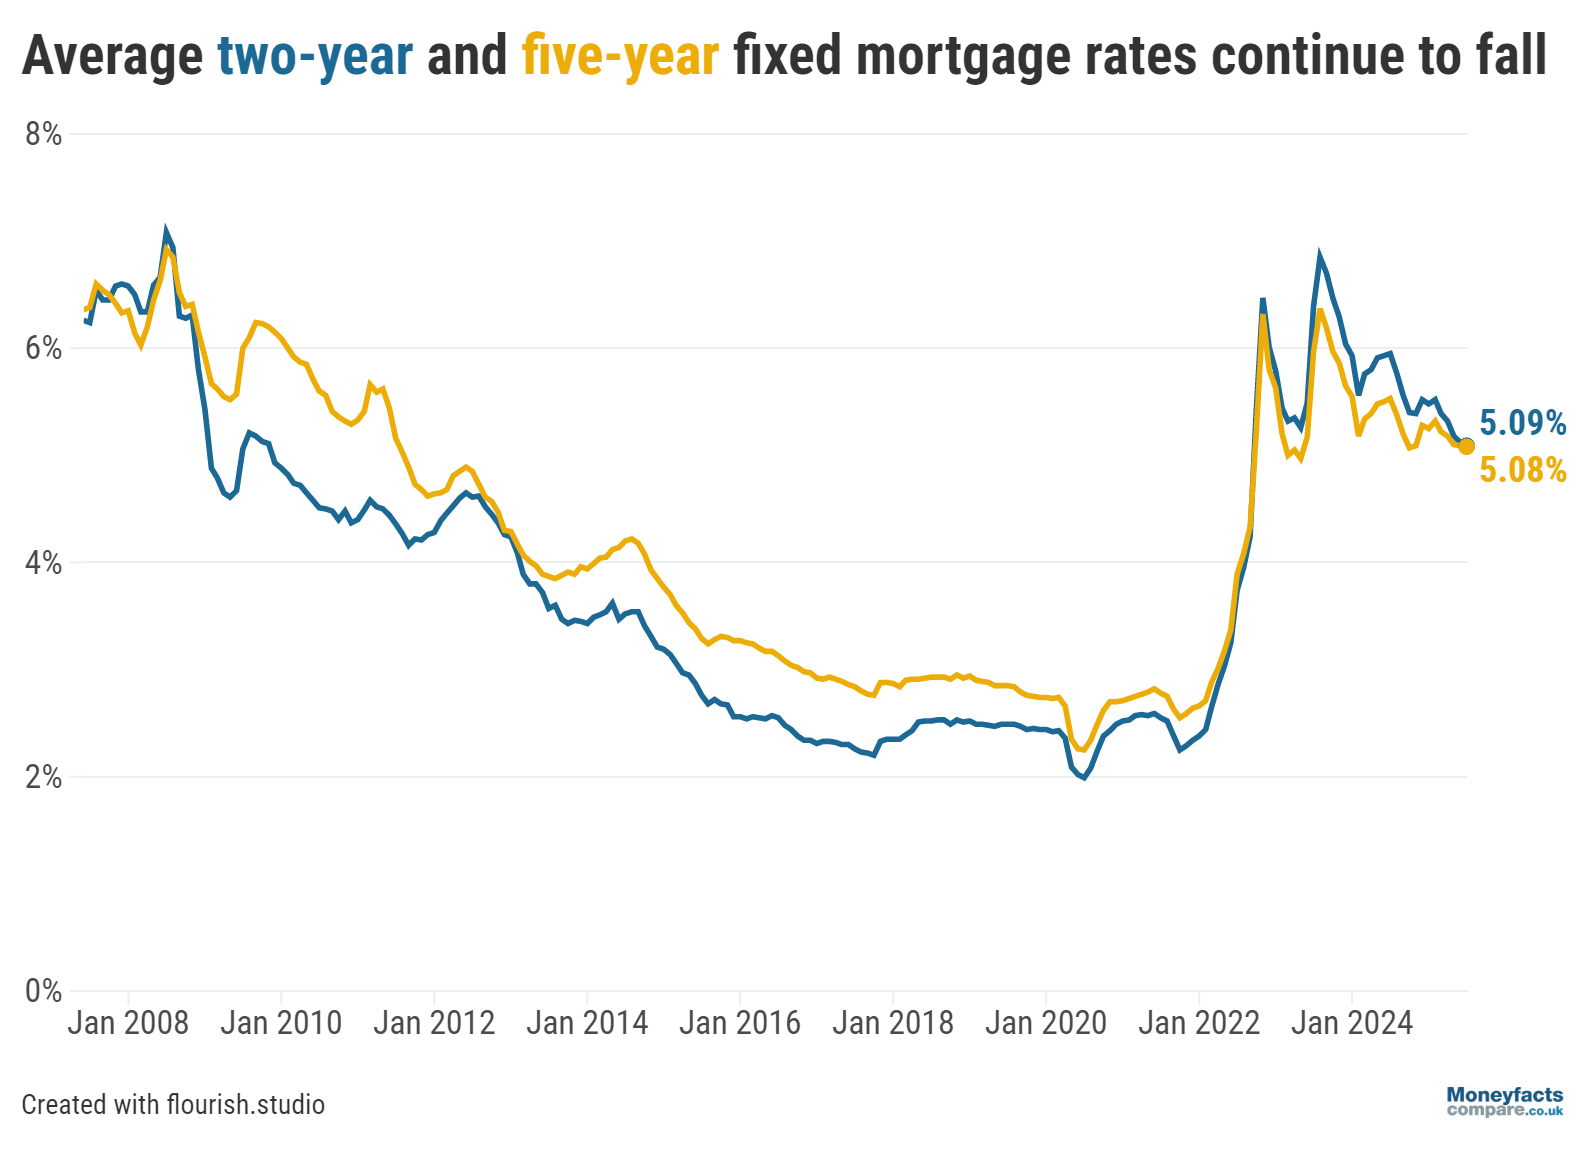 Average Mortgage Rates Continue To Fall For Fifth Consecutive Month
Another fact: in the UK, some people take ten-year terms. That’s not a mortgage; that’s a prison sentence. But you do you.
How to Decide (Fast)
Step one: breathe. Step two: ask yourself if you can handle uncertainty. If the thought of a rate hike makes you sweat, go five-year. If you thrill at the idea of a rate drop, go two-year.
Step three: ignore your nosy neighbor. They picked a variable rate and now eat ramen. Or they went fixed and missed a drop. Nobody’s perfect.
Remember: you can renew later. A two-year term ends, then you pick a new term. It’s like dating—you don’t marry the first bank.

